The White Paper Series
Beyond Woodchips: Why Australia's Hardwood Plantation Industry Must Move Up the Value Chain
By Tim Woods, lead developer of The Precinct project
For more than three decades, Australia's hardwood plantation industry has been built on a simple but largely successful business model: growing world-class plantation fibre for export to Asia's pulp mills. It has underpinned regional economies, attracted significant investment and established Australia as one of the world's most reliable suppliers of hardwood fibre.
Australia remains a premium provider of high-quality hardwood woodchips. Our plantation estate is among the world’s most productive and well-established, providing a significant resource that serves global pulp markets while also creating opportunities for new domestic markets.
But global markets are changing and have been for more than a decade. The export model that has served the industry so well is becoming more competitive.
Australian woodchip exports have fallen over the past year. While commodity markets inevitably fluctuate, the more significant story lies in changing demand from Australia's largest customer.
China's pulp industry is becoming increasingly diverse in its sources of hardwood fibre. A prolonged slowdown in China's domestic housing market has released significant volumes of locally sourced fibre into the supply chain, reducing reliance on imported woodchips and enabling manufacturers to produce satisfactory pulp from a lower-cost fibre mix.
Vietnam has the market
At the same time, competition from Vietnam has intensified. Vietnam now accounts for virtually all of China's growth in hardwood chip imports, with total Chinese imports increasing 11.4 per cent in early 2026. Vietnam’s growing position reflects, in part, a straightforward competitive advantage – its proximity to China.
In a global commodity market where freight is a significant component of delivered cost, Vietnam’s geographic proximity to China’s pulp mills provides its suppliers with a structural cost advantage.
This does not diminish the quality or reliability of Australian fibre. Rather, it highlights the exposure that comes with relying heavily on a single export pathway, particularly as competing sources of fibre become increasingly available.
This is a structural change
For many years, Australian hardwood plantations enjoyed a clear competitive advantage. High-quality Eucalyptus globulus, alongside Eucalyptus nitens, dependable supply and Australia's reputation as a politically stable trading partner meant local fibre attracted a premium whenever global pulp markets strengthened. Those advantages remain but the competitive environment is changing as Chinese manufacturers diversify supply sources, optimise fibre blends and reduce dependence on Australian imports.
Taken together, these trends point to something far more significant than a cyclical downturn. They represent a structural shift in the global fibre market and one that reinforces the importance of diversification.
The critical question for Australia is no longer whether we can compete harder in an increasingly crowded commodity market. It is whether exporting raw fibre should remain the only significant pathway for capturing the highest-value use of one of our most important renewable resources.
Diversification to meet sovereign needs
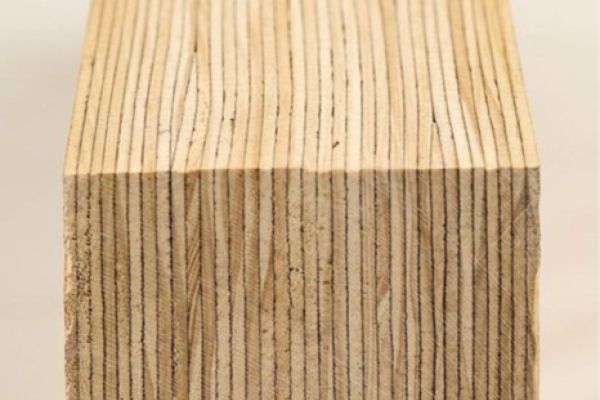
The same plantation estate is equally capable of producing higher-value engineered wood products that support advanced manufacturing of dwelling components and dwellings, skilled regional employment and sovereign industrial capability.
There is no better demonstration of this potential than Phase One of The Precinct project – the Hardwood Timber Manufacturing Hub.
The now delivered first feasibility study proves that instead of exporting low-value fibre and importing finished building products, Australia has an opportunity to capture more economic value through domestic processing and integration into the built environment.
The timing could not be better.
As export markets become more competitive, Australia faces an unprecedented housing challenge. Governments across the country are actively pursuing faster, more productive construction methods through prefabrication, modular housing and mass timber construction. The release of the National Housing Strategy at the recent ALP National Conference reinforces the growing policy focus on housing productivity, sovereign manufacturing and modern methods of construction.
From plantations, to products, to prefabrication
Yet despite this opportunity, Australia continues to import around $1 billion worth of engineered wood products, plywood and wood panels each year, while exporting much of the raw fibre needed to manufacture them.
One argument is that Australia is exporting the raw material while importing the finished products needed to build homes. The Precinct approach captures manufacturing jobs, innovation and economic returns offshore, despite Australia possessing the plantation resource, technical capability, relatively stable and growing domestic market to do that work locally.
Shifting from exporting fibre and importing value-added products, Australia has the opportunity to extend an integrated domestic manufacturing sector that converts plantation resources into engineered wood products, prefabricated building systems and integrated dwelling solutions.
This is precisely where The Precinct represents a fundamentally different proposition. The Precinct is being designed as an integrated, advanced manufacturing ecosystem that brings together plantation resources, engineered wood products, prefabrication, dwelling component manufacturing and circular economy principles, within a single regional supply chain.
Its importance lies in recognising the future for the value chain lies in integrated manufacturing that has a laser focus on delivering dwelling solutions, in the national interest.
Importantly, this transition aligns with the direction of government policy. Housing productivity, sovereign manufacturing, regional industrial development and lower-emissions construction are no longer separate policy objectives, they are increasingly part of the same national agenda. Developments to deliver this integrated agenda will define much of Australia’s housing future.
The latest export figures should therefore be viewed not as a hurdle for Australia's plantation industry, but as a catalyst for transformation opportunities. Australia has always adapted to changing markets. The next chapter will be led and won by maintaining our established global fibre markets while at the same time creating more value from our resources and developing sophisticated and integrated sovereign supply chains focussed on delivering the next generation of housing, employment and regional economic resilience.